Compare ordinary and preference shares in Singapore, including voting, dividends, liquidation rights, tax treatment and allotment steps for founders.
TLDR:
- Ordinary shares usually give shareholders voting rights and exposure to the company's future growth.
- Preference shares usually provide priority for dividends and repayment of capital, but often carry limited voting rights.
- The company constitution and issue terms determine the rights attached to each share class.
- Preference shares can suit investors seeking economic priority without the same level of control as founders.
- Singapore companies must obtain shareholder approval and complete the required ACRA filing when issuing new shares.
Ordinary shares and preference shares are distinct classes of company ownership with different voting, dividend and capital rights. ACRA states that ordinary shares usually have voting rights, while preference shares often have no voting rights and typically receive fixed dividends before ordinary shareholders.[1] Singapore founders should choose between ordinary and preference shares by deciding how control, investment returns, downside protection and future fundraising should be allocated. The company constitution and share terms must record the intended rights clearly.
What is the difference between ordinary and preference shares?
Ordinary shares usually prioritise ownership and voting participation, while preference shares usually prioritise defined economic rights.
Ordinary shareholders commonly vote on company matters and participate in value growth after higher-ranking claims have been satisfied. Ordinary shares do not give shareholders the right to receive or demand dividends, according to ACRA.[1]
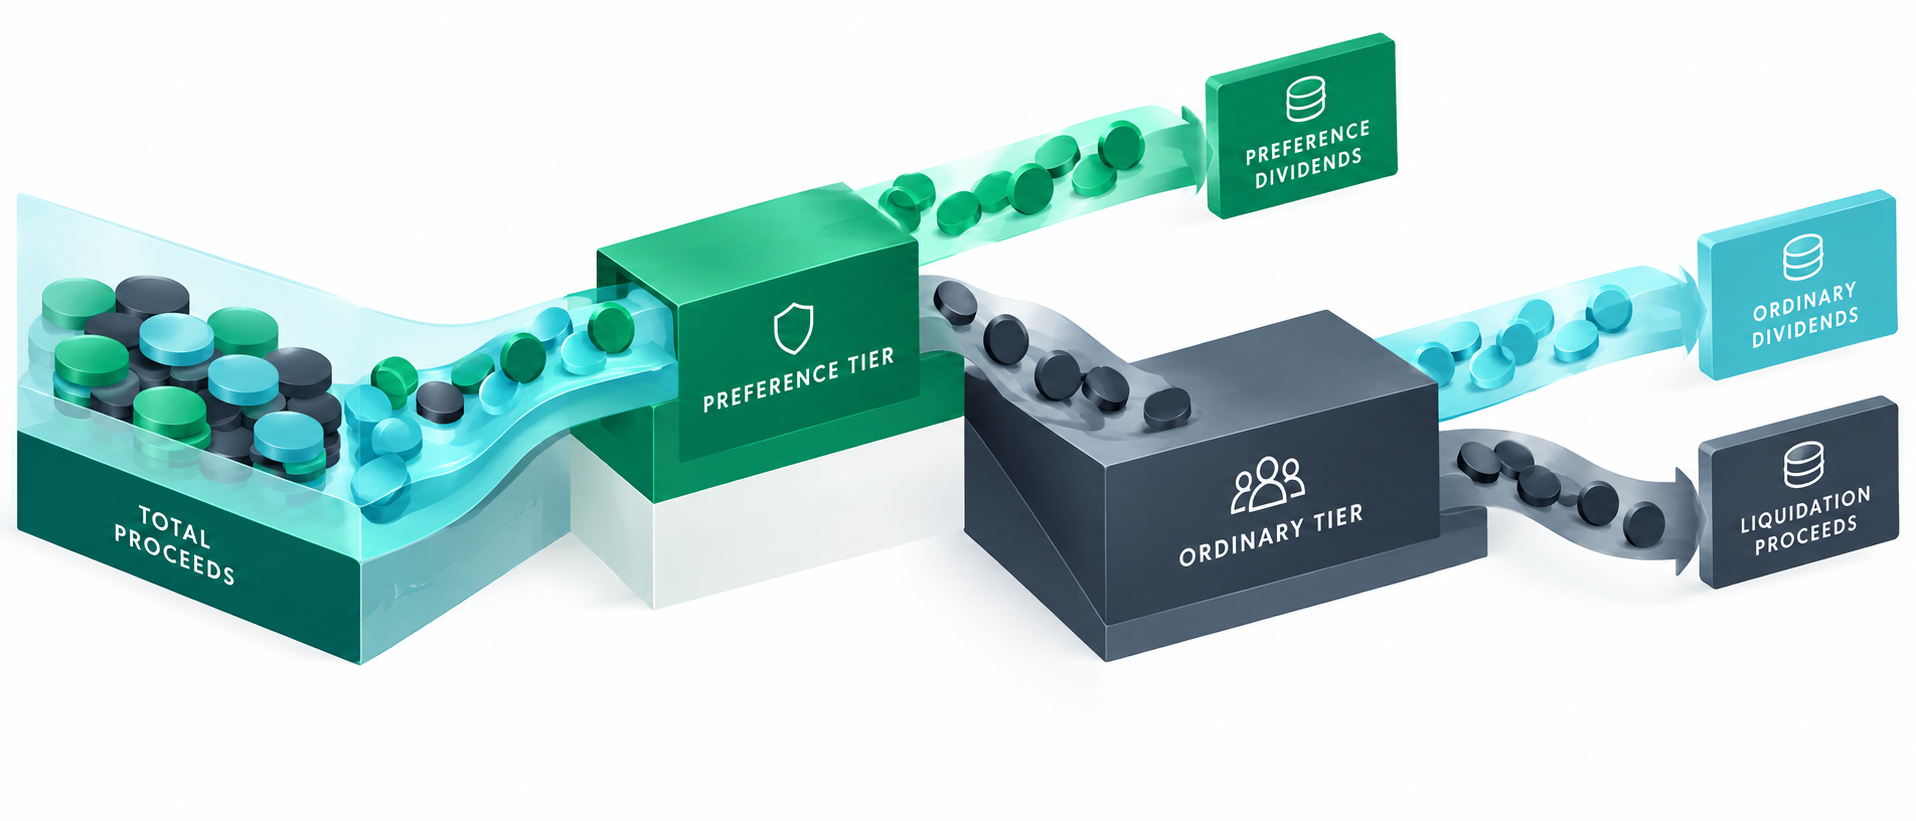
Preference shareholders typically receive fixed dividends and receive dividends before ordinary shareholders, according to ACRA.[1] Preference shareholders also get capital back first if the company is liquidated, although creditors and other legally senior claims remain relevant.[1]
The label attached to a share does not replace its legal terms. Section 75 of the Companies Act 1967 requires a company issuing preference shares to set out the holders' rights concerning repayment of capital, participation in surplus assets and profits, cumulative or non-cumulative dividends, voting, and priority of capital and dividend payments.[2]
How do the rights of ordinary and preference shares compare?
Ordinary and preference shares differ mainly in voting power, dividend priority, capital priority and flexibility.
| Feature | Ordinary shares | Preference shares |
|---|---|---|
| Ownership | Ordinary shares represent an equity interest in the company and commonly form its principal ownership class.[1] | Preference shares represent an equity interest carrying defined preferential or restricted rights.[1] |
| Voting | Ordinary shares usually have voting rights, although the constitution can create ordinary share classes with different rights.[1][2] | Preference shares often have no voting rights, but their precise voting rights must be stated in the constitution.[1][2] |
| Dividends | Ordinary shareholders do not have a right to receive or demand dividends merely because they hold ordinary shares.[1] | Preference shareholders typically receive fixed dividends before ordinary shareholders.[1] |
| Dividend accumulation | Ordinary dividends do not ordinarily accumulate as a fixed entitlement. | Cumulative preference shares can carry unpaid preferential dividends forward when the constitution and issue terms provide for accumulation.[2] |
| Return of capital | Ordinary shareholders usually rank behind preference shareholders for the return of share capital under the relevant share terms.[1] | Preference shareholders usually receive capital back before ordinary shareholders if the company is liquidated.[1] |
| Growth participation | Ordinary shareholders commonly retain greater exposure to increases in company value. | Preference shareholders may have capped, participating or convertible economic rights depending on the issue terms.[2] |
| Redemption | Ordinary shares are generally permanent equity unless transferred, bought back, cancelled or otherwise dealt with under the Companies Act 1967.[2] | Redeemable preference shares can be bought back by the company on agreed terms when the constitution authorises redemption and the statutory requirements are satisfied.[2] |
Who should choose ordinary shares?
Ordinary shares usually suit founders and investors who want voting participation and uncapped exposure to the company's value.
A founder-led private company often begins with one class of ordinary shares because a simple capital structure makes ownership percentages, voting and transfers easier to administer. ACRA describes ordinary shares as the most common share type and states that companies can create different ordinary classes, such as Class A and Class B, with different rights.[1]
Ordinary shares can also support employee equity arrangements when the company wants recipients to participate in future value growth. The company should define whether the employee class carries votes, dividends, transfer restrictions or compulsory transfer provisions.
Ordinary shares may be less attractive to an investor who requires a fixed or priority return. An ordinary shareholder cannot demand a dividend solely because the company has profits or cash, and the Companies Act 1967 states that no dividend is payable except out of profits.[2]
Who should choose preference shares?
Preference shares usually suit investors who negotiate economic priority, limited downside protection or a route to future conversion.
A venture investor may request preference shares that rank ahead of ordinary shares for specified dividends or repayment of capital. A founder may accept that economic priority while retaining voting control through ordinary shares, subject to the negotiated consent and veto rights.
A company can issue cumulative or non-cumulative preference shares. Cumulative terms carry an unpaid preferential dividend forward according to the constitution and issue terms, while non-cumulative terms do not carry an omitted dividend forward unless the governing documents provide otherwise.
A company can also issue convertible preference shares. ACRA states that convertible preference shares can provide fixed dividends for a set period and can then be converted into ordinary shares at an agreed price or remain unchanged; the conversion price must be stated in the company constitution.[1]
Preference shares require careful drafting because priority can apply differently to dividends, a sale, redemption and liquidation. Founders should avoid assuming that every preference share provides the same investor protection.
What terms should a company define for preference shares?
A company should define every economic, voting, conversion and exit right before issuing preference shares.
| Term | Question to resolve | Why the term matters |
|---|---|---|
| Dividend rate | Is the dividend fixed, variable or linked to a formula? | The rate determines the preferred return but remains subject to the legal rules governing dividend payments.[2] |
| Dividend priority | Does the preference dividend rank ahead of every ordinary class? | Priority determines which shareholders receive an available distribution first. |
| Accumulation | Is the preference dividend cumulative or non-cumulative? | Accumulation determines whether an omitted preferential dividend carries forward.[2] |
| Participation | Can the investor participate in additional ordinary dividends after receiving the preference amount? | Participation can materially increase the investor's economic return. |
| Voting | Which general, class-specific or protective matters can the holder vote on? | Voting terms allocate control and must be set out for preference shares.[2] |
| Liquidation preference | What amount is returned before ordinary shareholders participate? | The formula affects proceeds from a winding up and may also influence negotiated sale distributions. |
| Conversion | Is conversion optional, automatic or triggered by a qualifying event? | Conversion changes both ownership percentages and voting control. |
| Redemption | Can the company redeem the shares, can the investor request redemption, and on what date and price? | Section 70 of the Companies Act 1967 governs redeemable preference shares and requires the constitution to authorise the arrangement.[2] |
| Transfer restrictions | Can the holder sell or transfer the shares without consent? | Transfer rules affect founder control and investor liquidity. |
What documents are needed to create different share classes?
A company needs a suitable constitution, properly approved resolutions, clear issue terms and accurate statutory records.
The company constitution defines the rights and responsibilities of directors, shareholders and company secretaries, according to ACRA.[3] A company creating preference shares should ensure that its constitution contains the rights required by section 75 of the Companies Act 1967.[2]
The issue documents should state the number and class of shares, issue price, paid-up amount, dividend rights, voting rights, capital priority, conversion rights, redemption rights and transfer restrictions. A separate shareholders' agreement can address commercial protections, but the constitution and statutory filings must remain consistent with the intended class rights.
The company should prepare the relevant shareholder and board resolutions. Section 161 of the Companies Act 1967 states that directors must not exercise the company's power to issue shares without prior approval of the company in general meeting.[2]
The company must also maintain accurate share capital and shareholder information. ACRA requires a return of allotment to include the class and number of shares, issued capital, amounts paid and unpaid, allotment date and relevant shareholder details.[4]
How does a Singapore company issue ordinary or preference shares?
A Singapore company should settle the rights, obtain approval, allot the shares and complete the ACRA filing in the correct sequence.
- Review the existing constitution and capital structure. Confirm whether the constitution permits the proposed class and whether an amendment is required.
- Draft the share rights. Record voting, dividends, capital priority, participation, conversion, redemption and transfer provisions with enough precision to avoid competing interpretations.
- Approve any constitutional amendment. ACRA states that a company must pass a special resolution and file a Notice of Resolution when changing its constitution.[3]
- Obtain shareholder approval for the issue. ACRA states that the company must obtain approval through a general meeting before allotting shares, even if the constitution allows directors to decide on allotment.[4]
- Approve the allotment terms. The directors should approve the number of shares, issue price, consideration, class and recipient after the required shareholder authority is in place.[4]
- Receive the agreed consideration. The company should document cash and non-cash consideration and record any unpaid amount accurately.
- File the return of allotment through Bizfile. Company officers or an appointed corporate service provider can complete the filing.[4]
- Update the statutory and accounting records. For a private company, the allotment takes effect when ACRA updates the Electronic Register of Members after filing.[4]
- Issue the supporting documents. The company should provide the shareholder with the applicable share certificate and retain the resolutions, terms and accounting records.
ACRA states that an unresolved filing error may require an Order of Court when a Notice of Error cannot correct it.[4] Careful review before submission reduces that risk.
How do ordinary and preference shares affect dividends?
Share rights determine dividend priority, but available profits and a valid corporate decision determine whether a dividend can be paid.
Section 403 of the Companies Act 1967 states, “No dividend is payable to the share-holders of any company except out of profits.”[2] A preference dividend rate therefore does not permit payment from funds that cannot lawfully support a dividend.
Preference terms determine whether the holder receives a fixed amount, whether unpaid amounts accumulate and whether the holder participates in additional distributions. Ordinary shareholders receive distributions according to the rights of their class after applicable preferences have been addressed.
Directors and finance teams should check the constitution, issue terms, available profits and prior distributions before recommending or paying a dividend. The accounting records and resolutions should show how the amount was calculated and allocated among the share classes.
The broader process for declaring, documenting and paying distributions is covered in Dividends in Singapore: How Do Companies Pay Them?
Are ordinary and preference dividends taxed differently in Singapore?
The share label does not generally change the one-tier treatment of qualifying dividends paid by a Singapore resident company.
IRAS states that dividends paid to shareholders by a Singapore resident company under the one-tier corporate tax system are generally not taxable because the tax paid by the company is final, except for co-operatives.[5] The treatment applies to qualifying company dividends rather than turning solely on whether the recipient holds ordinary or preference shares.
IRAS states, “There is no need to withhold tax on dividend payments, even if there are withholding tax rates ascribed to dividends in some of our Avoidance of Double Taxation Agreements (DTAs). Singapore currently does not impose withholding tax on dividends.”[6]
A payment described commercially as a preference return can require closer review when the instrument has debt-like terms or when accounting and tax classification differ from its legal label. Companies should obtain tax and accounting advice for redeemable, convertible or unusually structured instruments.
Can ordinary shares be converted into preference shares?
A company can restructure share rights only through the required constitutional, shareholder and filing steps.
Section 75 of the Companies Act 1967 prevents a company from converting issued shares into preference shares unless the constitution sets out the required preference rights.[2] A proposed conversion should therefore begin with a review of the constitution and the existing rights attached to every affected class.
A conversion may require a constitutional amendment, shareholder approval, class consent and filings with ACRA. Existing shareholders should also review pre-emption rights, anti-dilution provisions, investor consent rights and contractual restrictions before approving the restructuring.
A company should document the commercial purpose and resulting cap table before implementation. A vague reclassification can create disputes over voting, dividends or exit proceeds even when the total number of shares remains unchanged.
Why do companies make mistakes when structuring share classes?
Companies make mistakes when commercial deal terms, constitutional rights and statutory filings do not match.
A generic preference-share label creates uncertainty when the documents omit dividend accumulation, voting, liquidation, conversion or redemption terms. Section 75 of the Companies Act 1967 requires the constitution to address the specified preference rights before allotment or conversion.[2]
An incomplete approval sequence can invalidate an issue. Section 161 states that a share issue made in contravention of the shareholder-approval requirement is void, and the consideration is recoverable.[2]
An inaccurate cap table can also produce conflicting ownership records. ACRA states that a private company's share allotment takes effect only when the Electronic Register of Members is updated after filing.[4]
A poorly modelled liquidation preference can surprise founders and ordinary shareholders during an exit. Companies should calculate several sale values before agreeing to participating, multiple or senior preferences.
How might ordinary and preference shares work in a founder funding round?
An illustrative funding structure can preserve founder voting control while giving an investor negotiated economic priority.
A Singapore technology company has two founders holding ordinary shares. An incoming investor requests preference shares carrying a specified dividend priority, a one-times return of the subscription amount before ordinary shareholders receive exit proceeds, conversion into ordinary shares and voting rights on defined protective matters.
The founders model the proceeds under low, medium and high exit values before agreeing to the terms. The company amends its constitution to record the preference rights, obtains the required approvals, allots the shares and files the return of allotment with ACRA.
The resulting structure gives the investor priority protection without transferring routine operating control. The resulting structure also makes the cap table more complex, so the company secretary and finance team maintain separate records for the ordinary and preference classes.
How can E&H Corporate Services help with a share structure?
E&H Corporate Services can coordinate the corporate secretarial, filing and accounting work required for a properly documented share structure.
Planning an ordinary or preference share issue? E&H Corporate Services can help review the intended capital structure, prepare corporate secretarial documents, coordinate resolutions, complete the relevant ACRA filings and align the statutory records with the company's accounting records. Legal or tax specialists can be brought into the process when an investment instrument requires bespoke advice.
Frequently Asked Questions
Do ordinary shareholders always have voting rights?
Ordinary shareholders usually have voting rights, but the constitution can create classes with different, limited or conditional rights.[1][2]
Do preference shareholders own part of the company?
Preference shareholders own equity in the company, subject to the rights and restrictions attached to their share class. Preference shares can carry limited votes while retaining priority economic rights.
Are preference dividends guaranteed?
Preference dividends are not automatically guaranteed merely because a fixed rate appears in the issue terms. Section 403 of the Companies Act 1967 states that no dividend is payable except out of profits.[2]
What is a cumulative preference share?
A cumulative preference share carries an unpaid preferential dividend forward when the constitution and issue terms provide for accumulation. A non-cumulative preference share does not carry an omitted dividend forward unless the governing terms state otherwise.
Can a startup issue both ordinary and preference shares?
A Singapore startup can issue different share classes when its constitution and approvals support the structure. ACRA recognises ordinary, preference, redeemable preference and convertible preference shares in its guidance.[1]
Do preference shares always rank first in a company sale?
Preference shares receive only the sale or capital priority created by their governing terms and applicable law. A company should distinguish a liquidation preference from contractual rights applying to a share sale.
Does Singapore impose withholding tax on preference dividends paid overseas?
Singapore currently does not impose withholding tax on dividend payments, according to IRAS.[6] A company should still review the instrument's classification and the recipient's circumstances when the return has debt-like features.
Does issuing preference shares require an ACRA filing?
A new allotment requires the company to complete the applicable return of allotment process and provide the class, capital and shareholder information required by ACRA.[4]
Related reading
Sources & References
- Deciding on Share Capital and Share Types — Accounting and Corporate Regulatory Authority
- Companies Act 1967 — Singapore Statutes Online
- Preparing or Adopting a Company Constitution — Accounting and Corporate Regulatory Authority
- Filing a Return of Allotment of Shares — Accounting and Corporate Regulatory Authority
- Dividends — Inland Revenue Authority of Singapore
- Payments that are Not Subject to Withholding Tax — Inland Revenue Authority of Singapore