Learn how GST reverse charge works in Singapore, who must apply it, which imports are covered, and how to calculate, report and document GST correctly.
TLDR:
- GST reverse charge requires affected Singapore businesses to account for GST on prescribed imported services and low-value goods as if they had supplied them.[1]
- GST-registered businesses generally fall within the rules when they are not entitled to full input tax credit.[1]
- A business accounts for output tax and may claim the corresponding input tax only to the extent allowed under the normal input tax recovery rules.[1]
- Overseas Vendor Registration covers certain overseas suppliers, while reverse charge places the accounting obligation on the Singapore customer.[2]
- Finance teams should review overseas invoices, contracts, expense claims and low-value goods purchases during every GST reporting period.
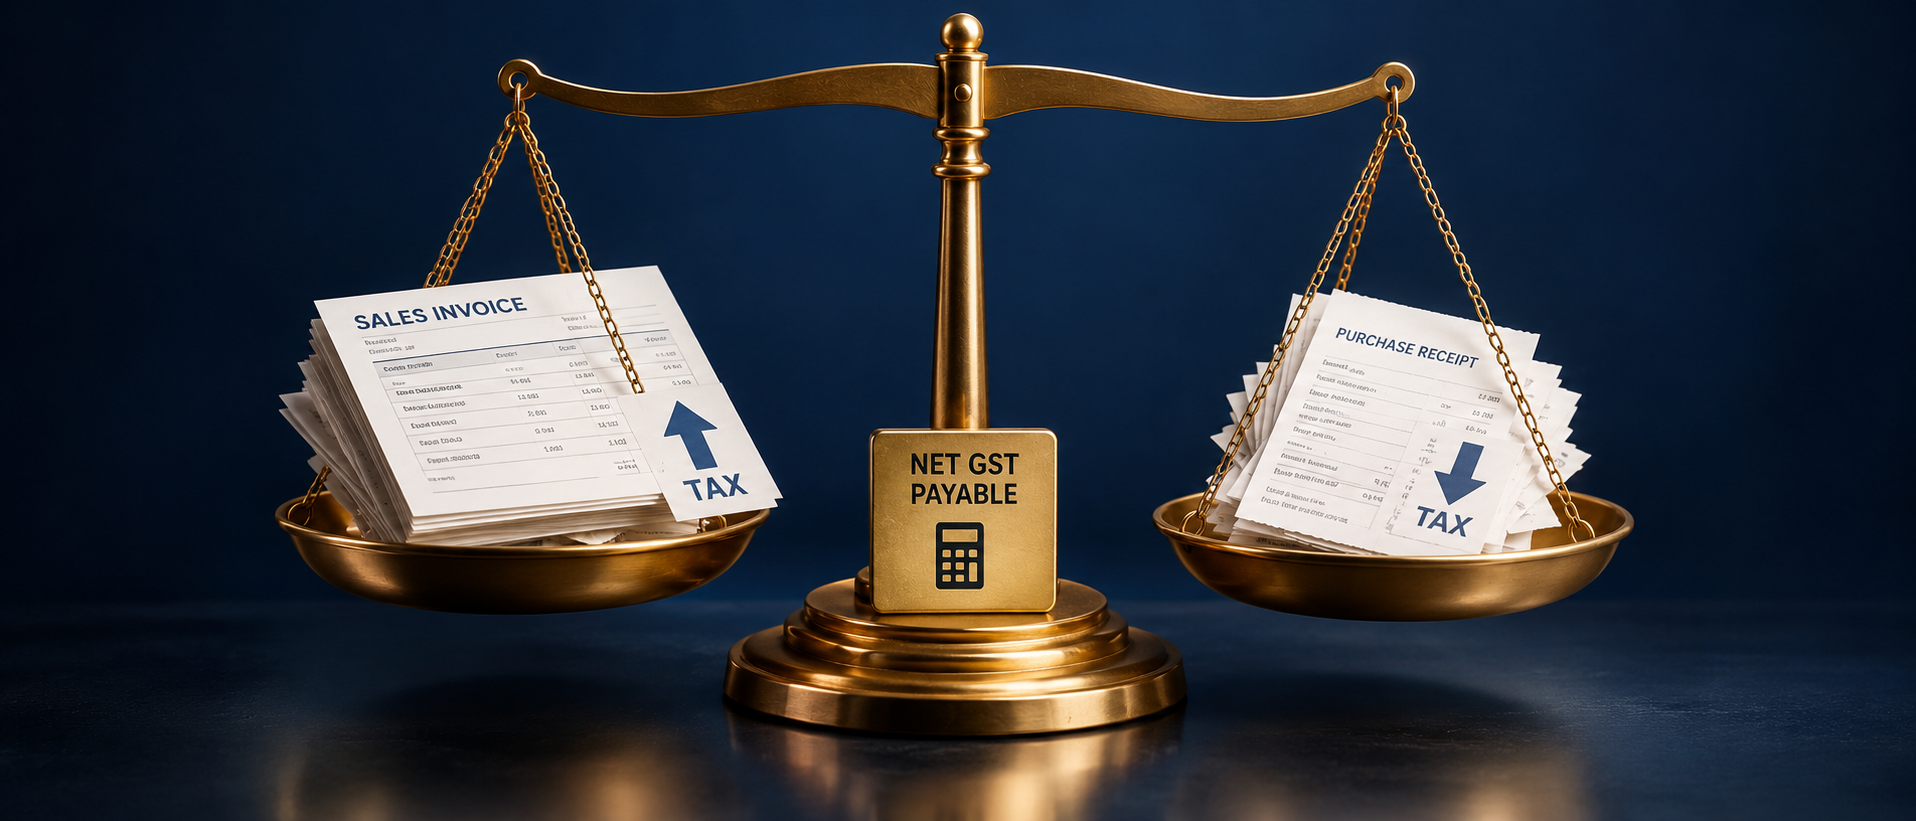
GST reverse charge is Singapore’s self-accounting mechanism for prescribed imported services and low-value goods received by affected businesses. IRAS requires a business subject to reverse charge to account for GST as if the business had supplied the goods or services to itself; the business may claim corresponding input tax only under the normal recovery rules.[1] The practical result is a net GST cost where the business cannot recover all of its input tax. For the wider registration framework, see GST in Singapore: Who Must Register and When?
What is GST reverse charge in Singapore?
GST reverse charge shifts responsibility for accounting for GST from an overseas supplier to the Singapore business receiving the prescribed import.
A conventional local purchase normally involves a GST-registered supplier charging GST to its customer. A reverse-charge transaction instead requires the affected customer to calculate output tax on the imported supply and report that amount in its own GST return.[1]
A corresponding input tax claim may be available, but the claim remains subject to the normal input tax recovery conditions. A business that can recover only part of its input tax will therefore bear the unrecoverable portion as a real GST cost.[1]
Reverse charge was introduced for imported services from 1 January 2020 and extended to imported low-value goods from 1 January 2023.[1]
Who must apply GST reverse charge?
GST-registered businesses that are not entitled to full input tax credit generally must apply reverse charge to their prescribed imported services and low-value goods.[1]
IRAS also requires certain non-GST-registered businesses to consider registration where the value of their imported services and low-value goods exceeds S$1 million over a 12-month period and the businesses would not be entitled to full input tax credit if they were GST-registered.[1]
| Business profile | General reverse-charge position |
|---|---|
| GST-registered business entitled to full input tax credit | Mandatory reverse charge generally does not apply.[1] |
| GST-registered business not entitled to full input tax credit | Reverse charge generally applies to prescribed imported services and low-value goods.[1] |
| Partially exempt business | Reverse charge can apply because the business cannot recover all input tax.[1] |
| Business conducting non-business activities | Reverse charge can apply where input tax would not be fully recoverable.[1] |
| Non-GST-registered business | Registration may be required when the imported services and low-value goods test and the input tax recovery condition are both met.[1] |
Banks, financial institutions, investment holding businesses, charities, residential property businesses and organisations with substantial non-business activities commonly require closer analysis because their input tax recovery may be restricted. Actual treatment depends on the business’s supplies, activities and applicable input tax rules.
Which imported services and goods are covered?
Reverse charge can cover prescribed imported services and low-value goods acquired from overseas suppliers for business or non-business use.[1]
Imported services can include professional advice, consultancy, software subscriptions, licences, digital platforms, management services, marketing, data services and other services supplied from outside Singapore. Each purchase must be assessed according to the nature of the supply rather than the description used on the invoice.
Low-value goods generally refer to goods located outside Singapore at the point of sale, delivered to Singapore by air or post and valued within the applicable import relief threshold.[2]
| Transaction | Initial review point |
|---|---|
| Overseas software subscription | Determine whether the supplier charged GST and whether the business is subject to reverse charge. |
| Foreign consultancy or legal services | Confirm that the service is imported and check whether an exclusion applies. |
| Regional management fee | Review the agreement, allocation basis, invoice and relationship between the entities. |
| Goods purchased from an overseas online seller | Determine whether the goods are low-value goods and whether GST was charged under Overseas Vendor Registration. |
| Locally supplied service | Apply the ordinary local GST rules rather than reverse charge. |
| Imported service that would be exempt or zero-rated if supplied locally | Review the specific exclusions in the IRAS reverse-charge guidance before accounting for GST.[4] |
Exclusions may apply to services that would be exempt, zero-rated or outside the scope of GST if supplied in Singapore. Finance teams should document the reason for excluding a material overseas purchase rather than relying only on the absence of GST on the supplier’s invoice.[4]
How is GST reverse charge calculated, and what does it cost?
A business generally calculates reverse-charge output tax by applying the prevailing GST rate to the value of the prescribed imported supply.[1]
The business then determines how much corresponding input tax it may claim under the normal input tax recovery rules. The simplified net cost is the reverse-charge output tax less the allowable input tax claim.
| Illustrative calculation | Amount |
|---|---|
| Imported consultancy services | S$100,000 |
| Reverse-charge output tax at 9% | S$9,000 |
| Assumed recoverable input tax at 40% | S$3,600 |
| Net GST payable from the transaction | S$5,400 |
The example assumes that the full S$100,000 is subject to reverse charge and that the business’s applicable input tax recovery analysis permits a 40% claim. Singapore’s prevailing GST rate is 9%.[1]
Foreign-currency invoices must be converted into Singapore dollars using an acceptable exchange-rate method. The business should apply its chosen method consistently and retain evidence supporting the conversion.[4]
How should a business report GST reverse charge?
A business should identify covered imports, calculate output tax, determine recoverable input tax and report both sides in the relevant GST return.[1]
- Compile overseas purchases. Extract overseas supplier invoices, employee expense claims, intercompany charges, software subscriptions and low-value goods purchases for the reporting period.
- Confirm the supplier and customer status. Check where the supplier belongs, whether Singapore GST was charged and whether the Singapore customer supplied its GST registration number.
- Classify each supply. Separate imported services, low-value goods, ordinary imported goods and transactions excluded from reverse charge.
- Determine the accounting period. Apply the prescribed time-of-supply rules, which generally consider when payment is made or an invoice is issued.[4]
- Convert the value into Singapore dollars. Use an acceptable and consistently applied exchange-rate method.[4]
- Calculate output tax. Apply the prevailing GST rate to the value subject to reverse charge.[1]
- Calculate allowable input tax. Apply the business’s input tax recovery method instead of automatically claiming the full corresponding amount.[1]
- Complete the GST return. Report the reverse-charge supply value and output tax in the applicable supply and output tax fields, together with the purchase value and allowable input tax claim in the relevant purchase and input tax fields.[4]
- Reconcile the return. Match the reported amounts to the general ledger, overseas purchase listing and supporting calculation before submission.
A consistent tax code in the accounting system can reduce omissions. Separate codes may be useful for fully recoverable, partially recoverable and non-recoverable reverse-charge transactions.
What records should a business keep for GST reverse charge?
A business should retain evidence identifying the supply, its value, its tax treatment and the basis of any corresponding input tax claim.
A practical reverse-charge file should contain:
- Overseas supplier invoices and credit notes
- Contracts, statements of work and purchase orders
- Proof of payment and invoice dates
- Evidence showing where the supplier belongs
- Foreign-currency conversion records
- Calculations of reverse-charge output tax
- Input tax recovery and partial exemption workings
- Evidence supporting any exclusion from reverse charge
- GST return reconciliations and relevant general-ledger entries
- Communications about whether the overseas supplier charged Singapore GST
GST records generally must be retained for at least five years, even if the business has ceased GST registration.[4] Electronic records should remain complete, readable and available for inspection throughout the retention period.
How does reverse charge differ from Overseas Vendor Registration?
Reverse charge makes the Singapore customer account for GST, while Overseas Vendor Registration requires qualifying overseas suppliers or electronic marketplace operators to register and charge GST on relevant supplies.[2]
| Feature | GST reverse charge | Overseas Vendor Registration |
|---|---|---|
| Party responsible for GST | Affected Singapore customer | Registered overseas supplier or electronic marketplace operator |
| Typical customer context | GST-registered business subject to reverse charge | Consumer or non-GST-registered customer receiving a covered supply |
| Invoice treatment | Overseas supplier generally does not charge Singapore GST on a business-to-business supply when the relevant customer information is provided | Overseas supplier charges Singapore GST on a covered business-to-consumer supply |
| Input tax position | Corresponding input tax is claimable only under normal recovery rules | GST charged may be claimable only if the recipient meets the normal requirements for an input tax claim |
A GST-registered customer should provide its GST registration number to the overseas supplier when requested for the supplier’s customer-status determination. An overseas vendor that treats the customer as a consumer may charge Singapore GST under the Overseas Vendor Registration regime.[2]
A business should contact the supplier to correct an invoice where GST appears to have been charged under the wrong customer classification. The business should not assume that an incorrectly charged amount can automatically be recovered as input tax.
What changed for GST reverse charge recently?
Singapore extended reverse charge from prescribed imported services to prescribed imported low-value goods from 1 January 2023.[1]
The expansion means that a reverse-charge review should no longer focus only on overseas services. Finance teams should also examine goods purchased from overseas vendors and marketplaces, particularly goods delivered to Singapore by air or post.
The related Overseas Vendor Registration regime also covers qualifying supplies of remote services and low-value goods by registered overseas vendors.[2] Supplier invoices and customer GST status therefore affect whether GST is collected by the vendor or self-accounted for by the Singapore recipient.
Why do businesses make GST reverse-charge errors?
Most reverse-charge errors arise from incomplete overseas purchase data, confusion with Overseas Vendor Registration or an incorrect input tax claim.
Common mistakes include:
- Treating every invoice without Singapore GST as outside the GST system
- Reviewing only consultancy fees while overlooking software, licences, digital services and intercompany charges
- Claiming the full corresponding input tax despite restricted recovery
- Assuming GST charged by an overseas vendor removes every reverse-charge issue
- Excluding imported low-value goods from the review
- Applying reverse charge in the wrong accounting period
- Using inconsistent foreign-exchange rates
- Failing to preserve calculations supporting an exclusion
A transaction-level review provides stronger support than a supplier-level assumption. A single overseas supplier may issue invoices with different GST treatments depending on the product, customer status and delivery arrangement.
How can an anonymised GST reverse-charge case work in practice?
A partially exempt Singapore business can incur a net GST cost even when its overseas supplier charges no Singapore GST.
An anonymised composite example involves a Singapore investment business purchasing S$20,000 of overseas software and advisory services. The overseas suppliers did not charge Singapore GST, but the business was GST-registered and unable to recover all of its input tax.
The business accounted for S$1,800 of reverse-charge output tax using the 9% GST rate.[1] An assumed 30% recovery entitlement produced an input tax claim of S$540, leaving a net GST cost of S$1,260.
The review also identified recurring software expenses paid through employee credit cards. Adding employee expense data to the quarterly overseas-purchase report helped prevent later omissions.
How can E&H Corporate Services help with GST reverse charge?
E&H Corporate Services can help businesses identify affected transactions, configure accounting records and prepare defensible GST calculations.
Need support with reverse charge or a wider GST review? E&H Corporate Services can review overseas purchases, input tax recovery, GST registration exposure and return reporting as part of its Singapore accounting and tax advisory services.
Businesses approaching the registration threshold should also review Singapore GST registration requirements before deciding whether their obligations arise under the ordinary taxable-turnover rules or the reverse-charge registration rules.
Frequently Asked Questions
The following answers address the most common practical questions about Singapore GST reverse charge.
What is GST reverse charge in simple terms?
GST reverse charge requires an affected Singapore customer to calculate and report GST on prescribed imported services and low-value goods as if the customer had made the supply.[1]
Does every GST-registered business apply reverse charge?
No. Mandatory reverse charge generally targets GST-registered businesses that are not entitled to full input tax credit, subject to the detailed IRAS rules.[1]
Does reverse charge apply to all imported goods?
No. The regime covers prescribed imported low-value goods, while other imported goods remain subject to the applicable import GST and customs processes.[1]
Can a business claim the same GST amount as input tax?
A business can claim corresponding input tax only to the extent permitted by the normal input tax recovery rules. Restricted recovery can cause the reverse charge to create a net GST cost.[1]
What should a business do if an overseas vendor charges Singapore GST?
The business should verify whether the supplier applied Overseas Vendor Registration correctly and whether the supplier treated the customer as GST-registered. An incorrect invoice should be raised with the supplier rather than treated automatically as valid input tax.[2]
Can reverse charge make a non-GST-registered business register for GST?
Yes. Registration may be required where imported services and low-value goods exceed S$1 million over a 12-month period and the business would not be entitled to full input tax credit if registered.[1]
When should reverse-charge GST be reported?
Reverse-charge GST should be reported in the applicable GST accounting period under the prescribed time-of-supply rules, which generally consider invoice and payment timing.[4]
Related reading
- GST in Singapore: Rates, Registration, Exemptions and Filing
- What is the reverse charge on imported services?